Titanium Price Today (2 Nov 2026): Plate, Tube, Rod & Wire
Titanium Price Today (2 Nov 2026): Plate, Tube, Rod & Wire
Titanium Price Today: China Market Report for Plate, Tube, Rod, Wire & Sponge Titanium
October was a down month, not a flat one. Grade 0 sponge titanium closed October at RMB 41,000–43,000/t, about RMB 2,500 below the start of the month, and Grade 1 civil sponge slipped to RMB 40,000–42,000 with some deals near 39,500. Producers are still running essentially at full capacity despite negative margins, so most Chinese market commentary now treats a break below RMB 40,000/t during November as the base case. If you buy standard industrial grades, there is no reward for urgency; if you buy certified alloy grades, prices have not followed.
Full price table
Latest trading week, 28–31 October 2026. RMB prices are China domestic ex-works including 13% VAT. USD figures are indicative conversions at 6.7146 only — they are not export prices.
| Product | China grade | ASTM equiv. | Size / spec | Price (RMB) | Ind. USD |
|---|---|---|---|---|---|
| Sponge titanium | |||||
| Sponge, Grade 0 | 0# | — | — | 41,000–43,000 /t | $6,100–6,400 /t |
| Sponge, Grade 1 civil | 1# | — | — | 40,000–42,000 /t | $5,950–6,250 /t |
| Sponge, Grade 2 | 2# | — | — | 39,000–41,000 /t | $5,800–6,100 /t |
| Ingot & slab | |||||
| Pure titanium ingot | TA1 | Gr1 | — | 51,000–53,000 /t * | $7,600–7,900 /t |
| Pure titanium ingot | TA2 | Gr2 | — | 50,000–51,000 /t | $7,450–7,600 /t |
| Alloy ingot | TC4 | Gr5 | — | 62,000–64,000 /t | $9,230–9,530 /t |
| Slab, pure titanium | — | — | — | 64,000–65,000 /t | $9,530–9,680 /t |
| EB-melted slab | — | — | — | 66,000–68,000 /t | $9,830–10,100 /t |
| Plate, sheet & coil | |||||
| Hot-rolled medium plate | TA1/TA2 | Gr1/Gr2 | 1.2 m width | 63,000–67,000 /t | $9,380–9,980 /t |
| Cold-rolled sheet | TA1 | Gr1 | 2.0 mm | 72,000–76,000 /t | $10,700–11,300 /t |
| Hot-rolled black coil | pure Ti | — | — | 70,000–73,000 /t | $10,400–10,900 /t |
| Cold-rolled coil | pure Ti | — | — | 78,000–83,000 /t | $11,600–12,350 /t |
| Alloy plate | TC4 | Gr5 | standard sizes | 160,000–180,000 /t | $23,800–26,800 /t |
| Alloy plate | TA10 | Gr12 | — | 140,000–160,000 /t | $20,850–23,800 /t |
| Tube & pipe | |||||
| Tube hollow / pierce billet | pure Ti | — | — | 82–85 /kg | $12.2–12.7 /kg |
| Seamless tube | TA1 | Gr2 | 20–30 mm | 120–125 /kg | $17.9–18.6 /kg |
| Welded tube | TA1 | Gr2 | — | 105–110 /kg | $15.6–16.4 /kg |
| Rod, bar & wire | |||||
| Bar, peeled | TA1 | Gr1 | 20–40 mm | 105–110 /kg | $15.6–16.4 /kg |
| Bar, peeled | TC4 | Gr5 | 20–40 mm | 120–125 /kg | $17.9–18.6 /kg |
| Wire | pure Ti | Gr1/Gr2 | 2–5 mm | 140–220 /kg | $20.9–32.8 /kg |
| Wire | TC4 | Gr5 | 2–5 mm | 240–280 /kg | $35.7–41.7 /kg |
| Flanges, fittings & machined parts | |||||
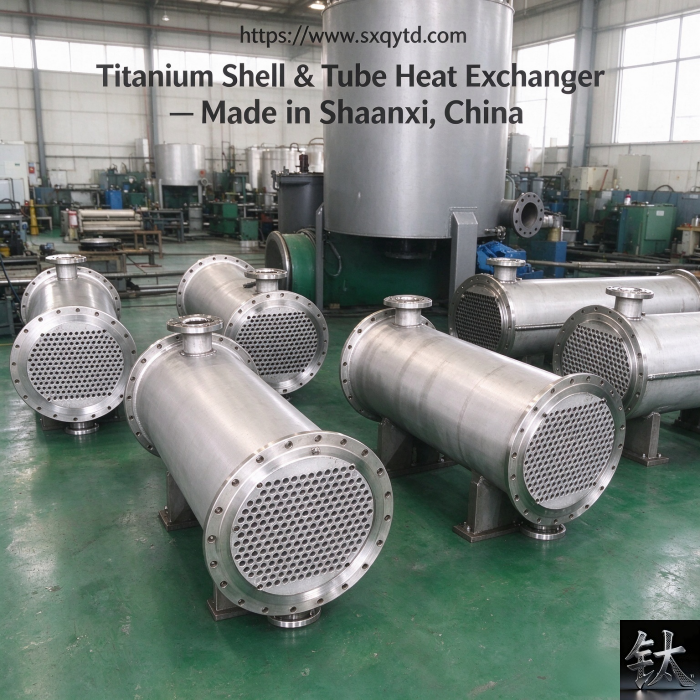
| Flanges, fittings, agitators, coils, heat-exchanger and reactor components — Quoted per order | — | ||||
* TA1 ingot shows two concurrent quotes: 51,000–53,000 RMB/t in producer/trader assessments, while one Baoji platform posted 55,000–56,000 on 31 October. Treat the spread as the market range until quotes converge.
What moved today — and what did not
Moved
- Sponge titanium, all grades down. SMM data to 30 October put Grade 0 at 41,000–43,000 RMB/t, average 42,000 — down RMB 2,500 from the start of October. Grade 1 civil prints reached 39,500 in late October, the first sub-40,000 trades of this cycle.
- Ore continuing to fall. The Panxi titanium ore index printed 1,101.25 on 29 October, down 76.25 in a single day after major Panzhihua producers cut list prices again. Mysteel assessments put Panzhihua 46% ore at 1,060–1,120 RMB/t ex-works excluding VAT; some spot postings were still 1,200–1,230 — an unusually wide spread that reflects the big producer's price reset working through smaller traders.
- TA1/TA2 ingot under pressure. Civil-grade ingot is being offered below RMB 50,000/t at the low end, and melting margins, not ingot prices, are where mills are losing ground.
Did not move
- TC4 (Gr5) ingot held 62,000–64,000 RMB/t and TC4 plate held 160,000–180,000 — aerospace and military order books are still covering capacity in the alloy segment.
- Bar and tube lists unchanged (TA1 bar 105–110, TC4 bar 120–125, seamless tube 120–125 RMB/kg), but with order books thinning, list stability is masking deal-level concessions — Chinese commentary describes civil titanium as "stable on paper, falling in transactions."
- Welded tube 105–110 RMB/kg. Welded tube runs 30–40% below seamless at the same size, and cost-sensitive chemical projects are systematically shifting toward it.
Q3 earnings landed in the last week of October, and the sector reported losses across the board: the Baoji mill leader's nine-month net profit fell 29.38% year on year (−30.05% in Q3 alone), Western Superconducting fell 59.62%, Western Metal Materials fell 19.95% and stated flatly that "titanium product orders declined," and Jinpeng Titanium turned to a loss in Q3. National sponge capacity is projected at 411,000 t/yr by end-2026 running near 70% utilization. Losses are not triggering cutbacks — that is why the price floor keeps giving way.
Three forces holding prices here
1. Full capacity despite negative margins
Semi-process sponge producers operate at roughly −5% to −6.5% margin, yet the industry is running essentially flat out, with high inventories and small-order, stock-replenishment-only trading. The 60,000 t/yr Anning integrated project (first furnace tapped 26 September, ramping through October) adds volume at an estimated break-even near RMB 40,000/t — below the average producer's cost. Output discipline, not demand, is the variable that could stabilize price, and there is no sign of it yet.
2. Just-in-time demand only
Chemical and civil buyers are placing small, need-based orders with heavy price pressure and no forward stocking. Aerospace and military demand is healthy but too small in tonnage to offset the chemical segment. The "Golden September, Silver Ten" seasonal pickup failed to materialize on both ends.
3. Trade barriers squeezing the export outlet
India reinstated anti-dumping duties on Chinese TiO2 on 24 October — USD 460–681/t for five years — joining the EU and Brazil; UK and Japan investigations are ongoing. September TiO2 exports of 175,850 t (+22.04% MoM) still look strong on paper, but the outlet is narrowing while domestic TiO2 (rutile, sulfur process: 12,800–15,200 RMB/t) stays weak, which feeds pressure back up the chain to sponge.
What this means if you are buying now
Standard industrial grades (Gr1/Gr2 civil plate, bar, welded tube)
Prices are still falling. Do not lock annual or multi-quarter pricing. Buy per order or on very short coverage (under one month), and quote your volume when the market is falling — high mill inventories are working in the buyer's favor right now. Concessions will show up in lead time, payment terms and tolerance bands faster than in headline lists.
Programme volumes (3–12 months of usage)
Split into batches and shorten price-lock windows to a month or less. Chinese market commentary broadly expects the RMB 40,000 sponge line to break in November; if that happens, a second leg down in civil titanium prices is likely with a short lag. There is no need to chase — waiting costs nothing while the trend is down.
Certified & project-critical (TC4/Gr5, TA10/Gr12, aerospace, project deadlines)
This is a different market: TC4 ingot and plate have not followed sponge down. Lock delivery certainty and certification paperwork first; expecting a material discount here will cost you schedule, not save you money. For non-standard parts — agitators, coils, heat exchangers, machined components — negotiate the fabrication fee separately from material, since material cost is transparent to everyone and fabrication capacity is where the flexibility is.
How to read these prices
- All RMB prices are China domestic, ex-works, including 13% VAT. These are not export prices — FOB/CIF quotes differ because of VAT/rebate treatment, export packaging, inland freight, order volume and payment terms. Ask us for an export quote; do not assume one.
- USD figures are indicative conversions at the CFETS central parity of 6.7146 (2 November 2026) and move with the currency, not with the metal.
- Grade equivalents: TA1≈Gr1, TA2≈Gr2, TC4≈Gr5, TA9≈Gr7, TA10≈Gr12. Chinese GB and ASTM tolerances are similar but not identical — confirm the standard on your drawing.
- Sponge is quoted by grade: 0# (highest), 1#, 2#. "Civil" grades follow the chemical/consumer market; aerospace-certified material trades separately and has not tracked these declines.
- Flanges, fittings and machined parts carry no public list price — every quote is order-specific, so ranges for these items are not published here.
Looking for current stock and short lead times on plate, tube, bar or custom parts? See our Titanium Plate and seamless tube pages, or send your drawing for a same-week quotation from Baoji.
Sources: Shanghai Metals Market (SMM) and China Nonferrous small-metals spot assessments; Mysteel titanium and titanium dioxide price assessments; Northern Nonferrous Metals Network daily market
reports (28–31 Oct 2026); producer and trader quotations for finished mill products; General Administration of Customs monthly export statistics. FX reference: CFETS central parity rate, 2 Nov 2026.
Prices reflect the latest available trading week (26–31 October 2026); no new list changes were posted over the 31 Oct–1 Nov weekend. Figures are indicative market reference prices, not offers. Actual transaction prices depend on specification, quantity, schedule and payment terms. This report is general market information and does not constitute a trading or investment recommendation.
- Titanium Price Today (Oct 26, 2026): China Market Report
- Titanium Price Today (23 Oct 2026): Plate, Tube, Rod & Wire
- Read titanium wire and titanium alloy wire: diameter classification
- Titanium wire: from brand selection to manufacturing process (2026 r
- Read titanium tube and titanium alloy tube: OD classification + comm
Contact Person: Wang Xiaoning
Tel: +86-917-355-7966
Email: sales@sxqytd.com
WhatsApp: +86 188 2967 9311
Company: Shaanxi Qianyi Tuoda Technology Co., Ltd
Address: Floor 4, Building 4, No. 188 Gaoxin Avenue, High-tech Zone, Baoji City, Shaanxi Province, China